


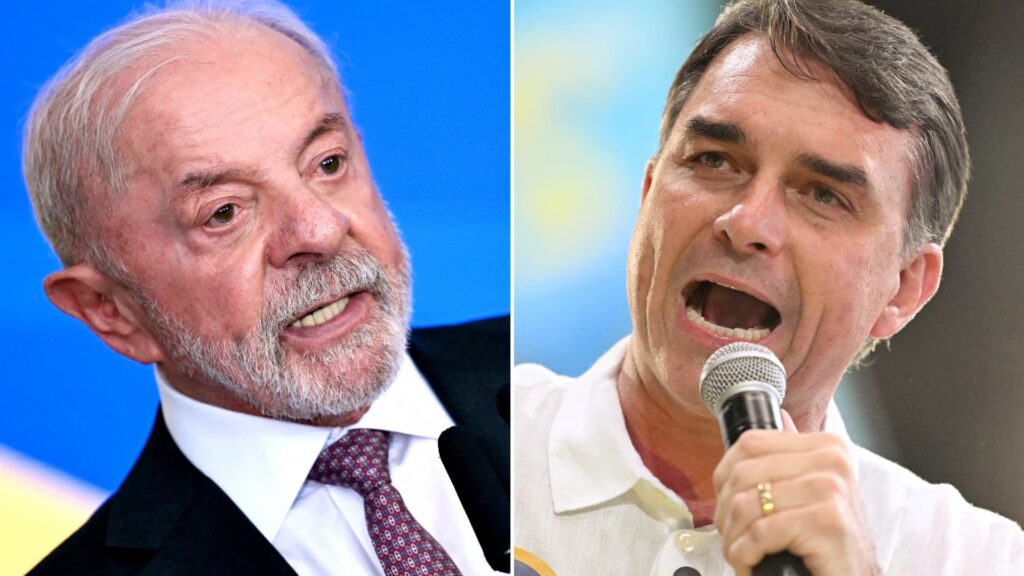
This combination of file pictures created on Sept. 29, 2026, shows Brazil’s President Luiz Inacio Lula da Silva at the Planalto Palace in Brasilia on Sept. 16, 2026; and Brazil’s right-wing Presidential candidate Flavio Bolsonaro at the Maracanazinho gymnasium in Rio de Janeiro, Brazil, on Aug. 22, 2026.
Evaristo Sa | Mauro Pimentel | Afp | Getty Images
With the first round of Brazil’s presidential election taking place Sunday, Wall Street is gearing up with starkly different market predictions depending on the outcome of the neck-and-neck race.
„The Brazil trade is: Does Lula win or does Bolsonaro win?“ said Fernando Marengo, chief economist at Black Toro Global Investments.
Those names should sound familiar. Lula is 80-year-old leftist Luiz Inacio Lula da Silva, who is running for a fourth term against 45-year-old right-winger Flavio Bolsonaro, son of former President Jair Bolsonaro. If neither candidate gets more than 50% of the vote, a runoff will take place Oct. 25.
In short, if Bolsonaro wins, Wall Street expects a rally in the country’s bonds, currency and stocks.
As Bolsonaro has come from behind in the last few months, Brazilian stocks have moved higher along with his poll numbers. In a recent note to clients, JPMorgan noted that the MSCI Brazil „rose by 0.25% on average each day that Flavio gained in the polls.“
Kalshi markets now show Bolsonaro favored to win 60% to Lula’s 39%. Prediction markets are prohibited in Brazil, so they may not reflect local sentiment. In a note to clients, Aurora Macro Strategies senior advisor Richard Lapper said, „the balance has shifted toward Flavio over the past month, but not nearly as far as the prediction markets are pricing.“


Bovespa since Nov. 1, 2016
Bolsonaro is the favored candidate of the markets because he’s promising more fiscal discipline, something many economists say Brazil desperately needs. Debt-to-GDP stands at 81.9%, up 10% since Lula took office.
„We need a 3-3.5% fiscal adjustment to stabilize the public debt in relation to GDP,“ said Leonardo Porto, Brazil head economist for Citi. And it can’t just come from one-offs like privatization of state assets, he said. „Brazil needs a permanent fiscal adjustment.“
That means cutting spending or raising taxes — either of which will be difficult. Roughly 90% of Brazil’s budget is mandatory, some of it required by the constitution. At 32%, Brazil’s tax burden is already the highest in Latin America, according to the OECD, and its prospects for growth are low.
But there’s a lot to be gained if Bolsonaro wins and manages to implement a „robust reform agenda,“ said JPMorgan.
The firm looks to what happened under his father Jair when he was in power from 2016 to 2020. Bolsonaro Sr. managed to pass pension reform, which saved hundreds of billions of dollars. It imposed a minimum retirement age of 65 for men and 60 for women. Previously, men could retire at any age after working for 35 years, and women could retire at any age after working for 30 years. On average, the male retirement age was 56, and 53 for women.
During that period of reform, JPMorgan said Brazil’s 2-year yields fell almost to 4.7%, and the equity market gained 130%.
If Brazil enters another period of reform, JPMorgan analysts say interest rates could decline to their neutral level, 6% in real terms, 10% in nominal terms, and „we would be thinking about the MSCI Brazil upside potential between 21% and 41%.“ They believe the forward P/E could move from a current level of 8.6 to as high as 13.3, last seen in 2020.
The currency outcome is „bimodal,“ said JPMorgan, with USD/BRL moving to 5.50 if Lula wins and 4.90 if Bolsonaro wins.
The entire lower house, and one third of the upper house are also being decided in this election. The composition of the legislature will be a key factor regarding the ability to achieve reforms.
Black Toro’s Marengo points out that other recent victories by pro-business candidates in Latin America have led to big upside moves in the countries‘ stocks, bonds and currencies. He notes Colombia’s risk premium compression „was about 200 points, and it was one of the stock markets that rose the most — something similar to what happened in Peru.“ Marengo cautions some of the move is already priced in in Brazil.
As with all emerging markets, a key risk is rising global interest rates, and for Latin America in particular, the El Niño weather phenomenon which could lead to crop damage for agricultural exporters.
Disclosure: CNBC and Kalshi have a commercial relationship that includes customer acquisition and a minority investment.