
The Federal Reserve’s first rate hike since 2023 is starting to cool bond markets.
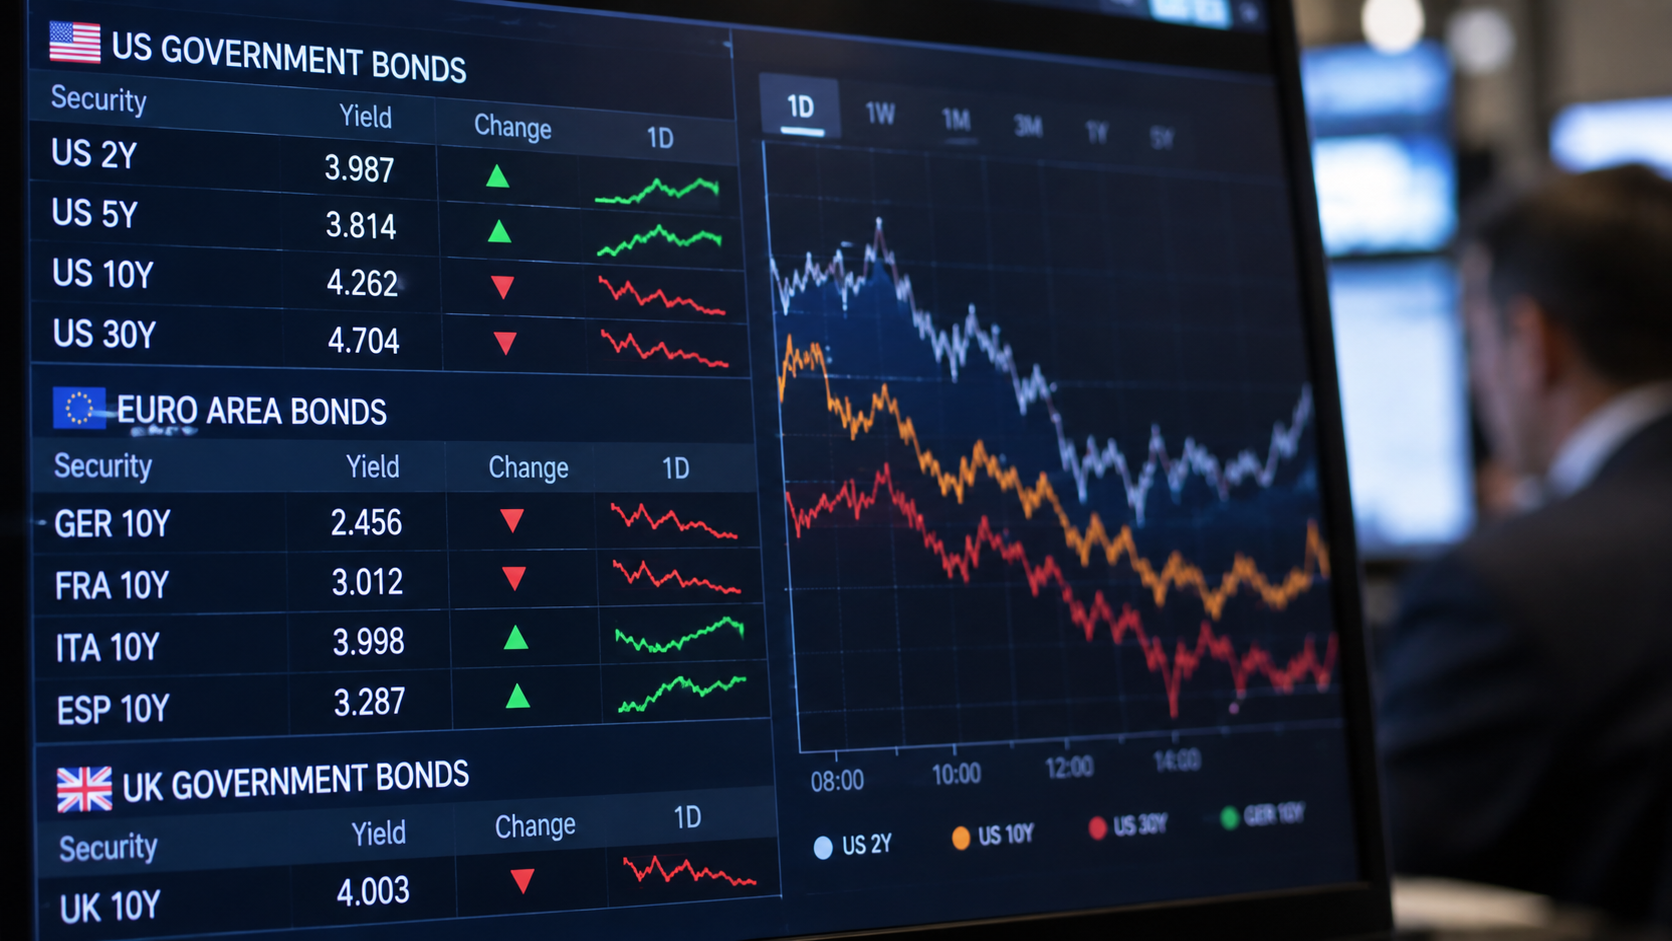
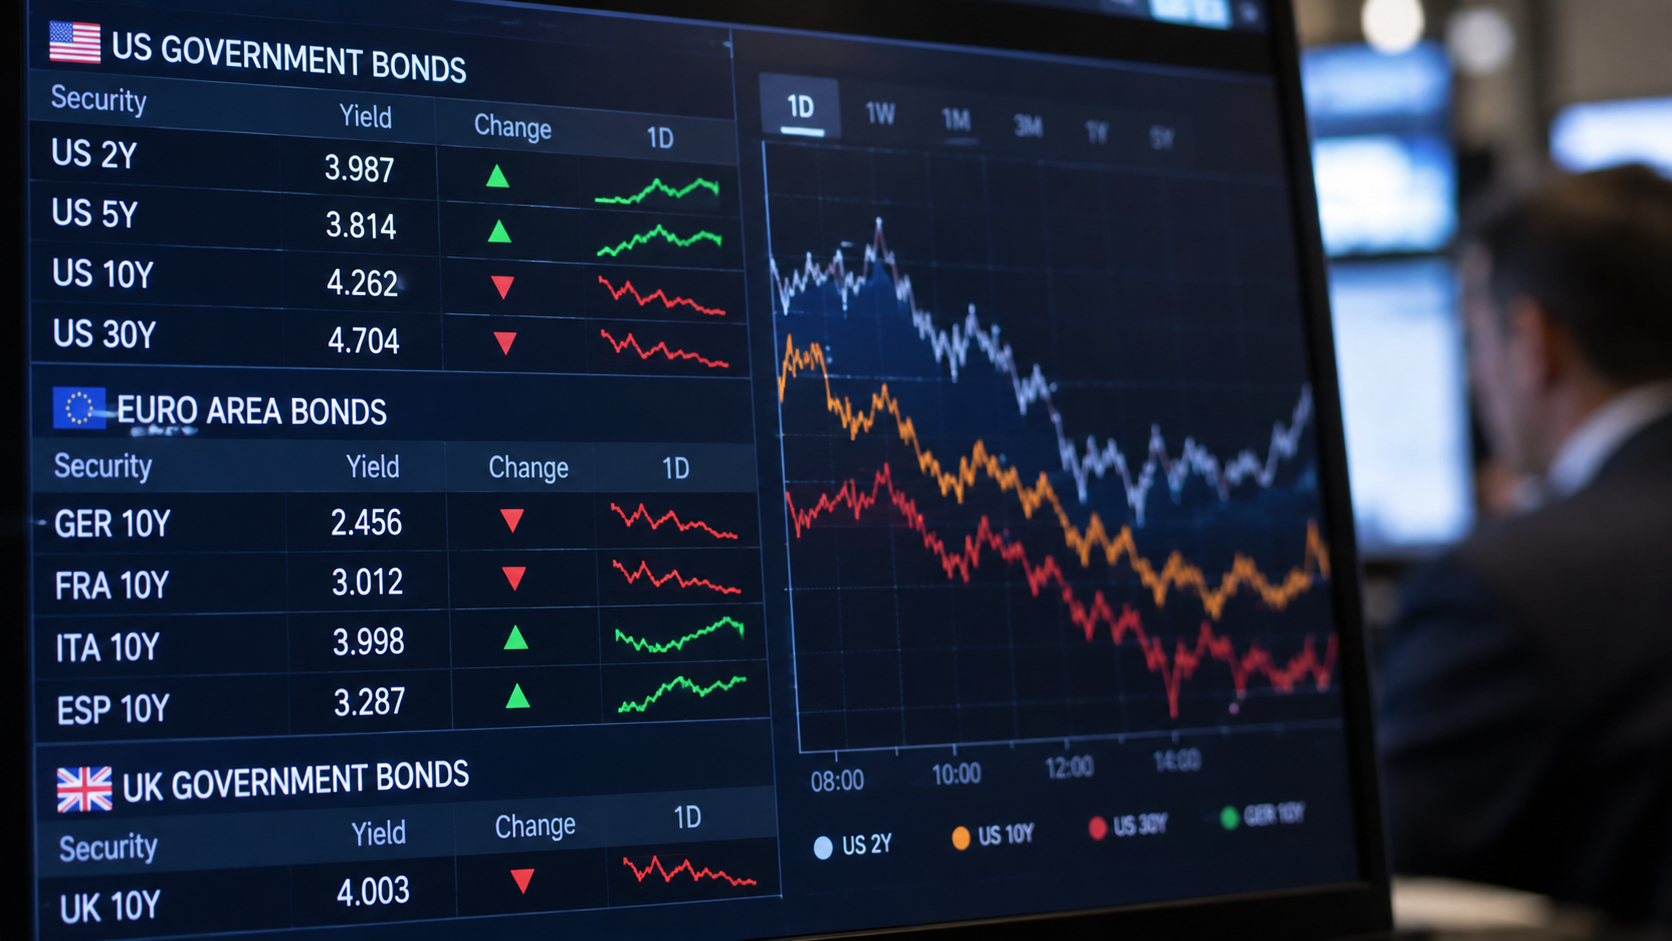
The 10-year Treasury yield fell Thursday, snapping an eight-day streak of gains, as investors weighed Chairman Kevin Warsh’s warning that inflation has stayed „too high for too long.“
The move came as investors shifted their attention to the Bank of Japan, which began a two-day policy meeting on Thursday ahead of its decision on Friday.
The retreat in yields followed a week of heavy selling that pushed average global government bond yields to a 19-year high.
The 10-year US Treasury yield fell about three basis points to 4.99%, ending an eight-day run of gains.
At 6:54 a.m. EDT, the yield was down almost two basis points at 4.988%.
Yields on comparable Australian government bonds fell about three basis points, while Japanese 10-year yields declined by less than one basis point.
However, British government bond yields, known as gilts, rose across maturities on Thursday morning as investors reacted to the Bank of England’s latest interest rate decision.
Fed hike brings temporary relief
The Federal Reserve raised its benchmark interest rate by 25 basis points on Wednesday to a target range of 3.75%-4%, marking its first increase since July 2023.
The move had been broadly anticipated by markets following a series of elevated inflation readings and growing pressure in the bond market.
Long-term government bond yields, which had touched multi-year highs during the selloff, eased as investors reassessed their inflation expectations.
US inflation remains well above the Federal Reserve’s 2% target, keeping the possibility of further monetary tightening in focus.
„The Fed had no choice but to give the market a hike or risk a much bigger bond market selloff,“ said Byron Anderson, head of fixed income at Laffer Tengler Investments in a Bloomberg report.
„The market narrative is on a collision course with the Fed from here on out, which means more volatility. A single rate cut is not going to placate this bond market for long and will not solve inflation.“
Warsh signals more rate hikes possible
Fed Chairman Kevin Warsh said during Wednesday’s press conference that inflation has been “too high … for too long.”
“We must be confident that underlying inflation is moving to our objective clearly and at sufficient speed,” he said, adding that the Federal Open Market Committee had decided “this standard has not been satisfied.”
Fed officials also signaled that another rate hike could come this year.
The latest projections showed 16 of 18 officials expected another increase, while four saw the possibility of two additional hikes.
Meanwhile, traders see a 51% chance of another Federal Reserve increase at the October meeting, up from nearly 44% a day earlier, according to the CME FedWatch tool.
„The history is clear that once the Fed begins raising rates, they do it multiple times; but the pattern is less clear about whether they will raise rates at consecutive meetings or leave rates unchanged at some of the meetings in between,“ said Chris Zaccarelli, chief investment officer at Northlight Asset Management in a Reuters report.
The Fed’s preferred inflation gauge stood at 3.7% in July, close to its highest level since 2023 and well above the central bank’s 2% target.
Warsh said summer inflation readings had not provided evidence that underlying price pressures had meaningfully improved.
The central bank’s stance has added to uncertainty over how far borrowing costs may rise, particularly after the recent surge in longer-term yields.
Warsh has also said that stronger economic growth, increased capital spending by large technology companies and geopolitical tensions have contributed to higher long-term borrowing costs.
What happens to bond yields now?
Bob Edwards, chief investment officer at Florida-based Edwards Asset Management, said in an emailed note on Thursday that the bond market’s biggest moves “are likely now in the rearview mirror.”
“There is now a good opportunity for investors after this big move to lock-in these elevated yields,” he said in a report by CNBC.
“If the Fed raises rates again, it would likely be at the December meeting, as the Fed is unlikely to announce interest rate changes at the October meeting, which is days before the midterm elections, for fear of appearing political.”
Hebe Chen, a market analyst at Vantage Global Prime, said the latest developments could have lasting implications for bond markets.
„For the bond market, this is likely to cast a long shadow rather than create a short-lived storm,“ she said in the Bloomberg report.
„The front end now has to price the possibility of further Fed tightening, while the long end is already wrestling with inflation, heavy issuance and fiscal concerns — meaning even when the initial volatility settles, the gravitational pull of higher yields may remain.“
BOJ decision comes into focus
Investors are now turning to the Bank of Japan, which began its two-day policy meeting Thursday.
All BOJ watchers surveyed by Bloomberg expect the central bank to raise its policy rate to 1.25% from 1%.
US Treasury Secretary Scott Bessent has expressed strong support for Japan’s decisive market and monetary steps to address the substantial undervaluation of the yen, according to a readout.
With markets having largely priced in a rate hike, attention is now turning to any signals BOJ Governor Kazuo Ueda may offer on the timing and pace of future increases.
„Markets are divided between those who see hawkish BOJ communication as helping lower bond yields by alleviating concern it is behind the curve on inflation, and others who see it as lifting yields by moving up terminal-rate bets,“ said Katsutoshi Inadome, senior strategist at Sumitomo Mitsui Trust Asset Management, in a Reuters report.
A Reuters poll of analysts showed expectations for the BOJ to raise its policy rate to 1.25% this month, 1.5% by the end of March next year and 1.75% in the second quarter of 2027.
Most analysts expect the terminal rate to reach at least 1.75%.
That leaves Ueda facing a delicate communication challenge when he addresses the press after Friday’s policy meeting.
The BOJ is keen to avoid committing to another early rate increase, but reiterating its cautious, „data-dependent“ approach could fuel renewed yen selling and push up import costs.
A more hawkish message, meanwhile, could add further pressure to Japan’s bond market.
Therefore, the BOJ decision could provide another test for global bond markets after a turbulent September.
The post Global bond yields retreat after Fed rate hike; BOJ decision sets up next market test appeared first on Invezz